7 Social Security Mistakes That Cost High Earners Thousands
Social Security might feel like a small piece of your retirement puzzle. If you’ve saved $2 million or more, what’s a few thousand dollars a month?
More than you think.
As of 2025, the maximum Social Security benefit at age 70 was $5,108 per month — over $61,000 per year. That’s guaranteed income, adjusted for inflation, for the rest of your life. And for your spouse after you’re gone.
Get the timing wrong and you could leave tens of thousands of dollars on the table. Here are seven mistakes I see high earners make — and how to avoid them.
Mistake 1: Not Understanding How Your Benefit Is Calculated
Your Social Security benefit is based on your highest 35 years of earnings, adjusted for inflation. The Social Security Administration averages those years to calculate your benefit.
Here’s what high earners often miss.
If you’ve been earning at or above the Social Security wage cap for 35 years, working longer won’t increase your benefit. The 2025 cap is $175,100. Back in 1990, it was $51,300. If you’ve hit the cap for 35 years, you’re already maxed out.
What to do: Log into SSA.gov and check your earnings record. Make sure every year is accurate. Errors happen — and they cost you money.
Mistake 2: Claiming Too Early
This is the big one.
You can claim Social Security as early as age 62. But if you do, your benefit is permanently reduced — by as much as 30% compared to waiting until full retirement age.
Here’s what that looks like for someone eligible for the maximum benefit in 2025:
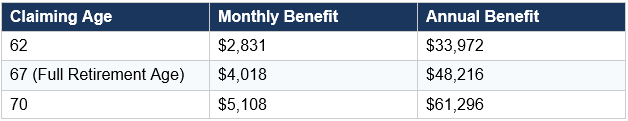
That’s a difference of over $27,000 per year between claiming at 62 and waiting until 70. Over a 25-year retirement, that adds up to nearly $700,000.
What to do: Unless you have health issues or urgent income needs, think carefully before claiming early. The math usually favors waiting.
Mistake 3: Assuming You Have to Claim When You Retire
Your retirement date and your Social Security claiming date don’t have to be the same.
Many people with significant savings can retire at 62 or 64, live off their portfolio for a few years, and delay Social Security until 70. This lets them lock in the higher benefit while also creating opportunities for Roth conversions and other tax strategies during those lower-income years.
What to do: Run the numbers. Retiring early and delaying Social Security might give you more lifetime income — and lower lifetime taxes.
Mistake 4: Ignoring the Tax Hit
Here’s something that surprises a lot of people: Social Security benefits are taxable.
If your combined income is above certain thresholds, up to 85% of your benefit can be taxed as ordinary income. For high earners, you’re almost certainly in that top bracket.
You can’t avoid this entirely. But you can reduce the impact with smart planning — like doing Roth conversions in lower-income years before you claim, or managing the timing of IRA withdrawals to stay in lower brackets.
What to do: Build a tax plan that accounts for Social Security. The years between retirement and age 70 are often your best window for tax-efficient moves.
Mistake 5: Forgetting About Your Spouse
If you’re married, your claiming decision affects two people — not just you.
Spousal benefits: A lower-earning spouse can receive up to 50% of the higher earner’s full retirement age benefit. But the higher earner has to claim first before the spousal benefit kicks in.
Survivor benefits: When one spouse dies, the surviving spouse can receive 100% of the deceased’s benefit. If the higher earner waited until 70 and locked in the maximum benefit, the survivor gets that larger amount for life.
Here’s why this matters. Among Americans 75 and older, 54% of women are widowed compared to just 20% of men. For most couples, the husband is the higher earner. If he claims early and dies first, his wife is stuck with a smaller benefit for the rest of her life.
What to do: Coordinate your claiming strategy as a couple. The higher earner should usually delay to 70 — not just for their own benefit, but to protect the surviving spouse.
Real financial planning for real life.
Riverbend is a fee-only, fiduciary advisor. Our plans are personal, shaped by your values and designed to help you build a full life.
Who We AreMistake 6: Underestimating How Long You’ll Live
A 2025 survey found that 64% of Americans are more afraid of running out of money in retirement than they are of dying. That fear is real — and Social Security can help address it.
Social Security is one of the few sources of retirement income that’s guaranteed for life and adjusted for inflation. The longer you live, the more valuable it becomes.
Here’s another thing to consider. Cost-of-living adjustments (COLAs) are applied as a percentage of your benefit. A larger benefit means larger annual increases. The 8.7% COLA in 2023 added $349 per month to a $4,018 benefit — but $444 per month to a $5,108 benefit.
What to do: If you’re healthy and have longevity in your family, waiting until 70 gives you the best hedge against outliving your money.
Mistake 7: Counting on Social Security to Replace Your Income
Social Security was never designed to replace your full paycheck. Even the maximum benefit only replaces about 35% of a $175,000 income — and just 15% of a $400,000 income.
For high earners, Social Security is one piece of the puzzle. You’ll also need income from investments, retirement accounts, maybe a pension, maybe rental income.
But here’s where Social Security shines: it’s guaranteed. When the market drops 20%, your Social Security check stays the same. That guaranteed income can keep you from selling investments at the worst possible time.
What to do: Build a retirement income plan that combines Social Security with other sources. Know where every dollar is coming from — and when.
Your Social Security Checklist
Before you claim, make sure you’ve thought through each of these:
☐ Checked your earnings record at SSA.gov for accuracy
☐ Calculated your benefit at 62, full retirement age, and 70
☐ Considered your health and family longevity
☐ Decided if you can delay claiming even if you retire early
☐ Factored in taxes on your Social Security income
☐ Coordinated with your spouse on timing and survivor benefits
☐ Built a complete income plan that doesn’t rely on Social Security alone
The Bottom Line
Social Security decisions are permanent. Once you claim, you can’t go back. For high earners, the difference between a good decision and a bad one can be hundreds of thousands of dollars over a lifetime.
Take the time to get it right.


